
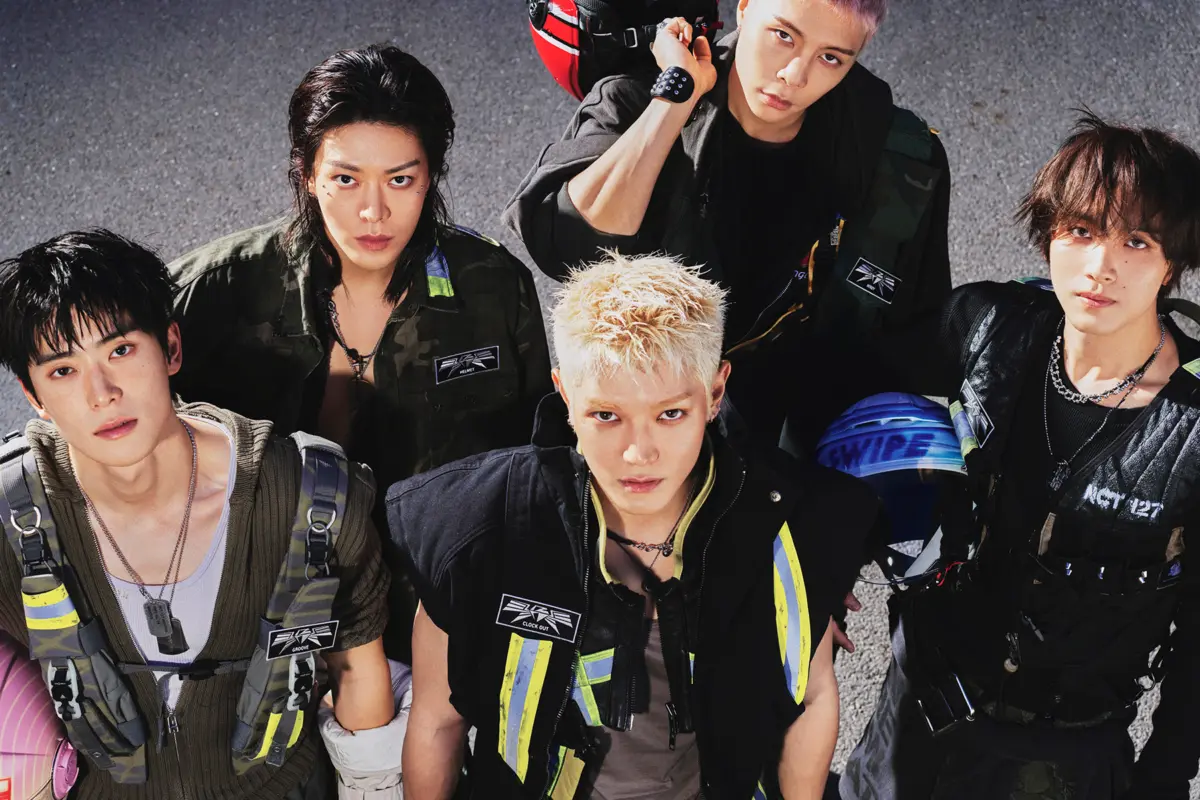
South Korean entertainment giant SM Entertainment, the powerhouse behind global K-pop phenomena like aespa, NCT, and NCT 127, saw its stock plummet by over 7% on Wednesday, November 4, following the announcement of an unprofitable third quarter. The company reported a significant 9% decline in overall revenue, primarily attributed to a downturn in physical and digital music sales and reduced concert revenue. This financial setback comes as the label pivots its strategic focus, emphasizing international expansion for its major artists, a move that appears to have temporarily impacted domestic release schedules and, consequently, quarterly sales figures.
Financial Performance Overview: A Deeper Dive into Q3 Results
SM Entertainment disclosed a revenue of 291.1 billion Korean won ($205.2 million) for the quarter. While a substantial figure, it represents a 9% decrease from the previous year. Operating profit also took a considerable hit, falling 26% year-over-year to 35.5 billion Korean won ($25 million). Perhaps the most striking figure was the net loss of 1.1 billion Korean won ($775,000) reported for the quarter, a stark contrast to the 44.7 billion Korean won ($31.5 million) profit recorded in the same period last year. Jeongmin Jang, CIO of SM Entertainment, explained during a conference call that this net loss was "primarily due to foreign exchange-related losses resulting from the appreciation of the Korean won." The strengthening of the domestic currency can negatively impact the translation of overseas earnings into Korean won, eroding profit margins derived from international activities.
The decline in core music sales was particularly pronounced. Sales of physical and digital music plummeted by 51% to 47.1 billion KRW ($33.21 million). The company reported selling 1.67 million copies of artist releases in the quarter, a sharp decrease of approximately 70% year-over-year in new album sales volume. This figure, while significant, was largely buoyed by the strong performance of NCT 127’s album BLINGY, which served as a primary driver within a period characterized by fewer major comebacks from other high-profile artists under the label.
Strategic Pivot: Overseas Expansion Over Domestic Release Volume
The management’s explanation for the reduced album sales volume points directly to a conscious strategic shift. Jang Jeongmin stated, "New album sales volume decreased by approximately 70% year over year as our major artists focused on expanding their overseas activities." This statement sheds light on a significant recalibration of SM Entertainment’s artist management and marketing strategy. Instead of maintaining a high frequency of domestic album releases to drive consistent quarterly sales, the label appears to be prioritizing the global footprint and long-term international market penetration of its artists.
This strategy typically involves extensive world tours, participation in international music festivals and award ceremonies, focused promotional activities in key overseas markets (e.g., North America, Europe, Southeast Asia), and collaborations with international artists or brands. While these activities are crucial for building a global fanbase and diversifying revenue streams beyond album sales, they often require artists to spend considerable time abroad, impacting their availability for studio recording and the rigorous domestic comeback cycles K-pop is known for. The trade-off, as evidenced by the Q3 results, can be a temporary dip in album sales during the transition period as the focus shifts from quantity of releases to quality and impact of global engagements.
The Evolving K-Pop Business Model: A Deeper Dive
SM Entertainment’s strategic pivot reflects a broader trend within the K-pop industry, where labels are increasingly looking beyond the saturated domestic market and traditional album-centric revenue models. For decades, K-pop’s success was heavily reliant on physical album sales, driven by dedicated fanbases collecting multiple versions, photocards, and other inclusions. While this remains a significant component, the industry is witnessing a shift towards maximizing intellectual property (IP) through diverse channels.
Labels like SM Entertainment, once pioneers in the "idol group" system, are now navigating a complex global landscape. The emphasis on overseas activities signifies an understanding that sustained growth lies in cultivating global fanbases that are willing to pay for concerts, merchandise, and unique experiences. This model, while potentially sacrificing immediate album sales in a given quarter, aims for higher-margin revenue streams over the long term, such as international touring, licensing deals, and bespoke global content creation. The challenge, as SM’s Q3 shows, is managing the transition period where the benefits of the new strategy might not yet fully offset the temporary decline in traditional revenue streams.
Bright Spots Amidst the Challenges: Diversifying Revenue Streams
Despite the overall financial downturn, SM Entertainment highlighted several "bright spots" in its earnings report, indicating successful diversification efforts that align with its global expansion strategy. The company’s share of major artists’ album releases and global concert activities, alongside the impact of IP licensing collaborations—collectively referred to as MD/licensing revenue—increased by a robust 23.5% year-over-year, reaching 62.1 billion Korean won ($43.78 million). This growth underscores the increasing importance of merchandise, brand partnerships, and the monetization of artists’ intellectual property beyond direct music sales.
Additionally, revenue generated from artists’ appearances saw a significant boost, rising by 21.3% to 29.2 billion Korean won ($20.6 million). This growth was driven by artists’ participation in high-profile international award ceremonies, music festivals, and lucrative advertising campaigns for apparel, cosmetics, and other industries. These appearances often serve as critical touchpoints for global brand building and fan engagement, further cementing artists’ international profiles and opening avenues for premium sponsorship deals. The strong performance in these segments suggests that the focus on overseas activities is indeed yielding positive results in areas less tied to the volume of new domestic music releases.
Industry Context and Peer Performance
To fully appreciate SM Entertainment’s Q3 performance, it’s essential to consider the broader K-pop landscape. The industry has seen unprecedented global growth in recent years, with groups like BTS, BLACKPINK, and Stray Kids achieving mainstream success in Western markets. Major labels like HYBE, JYP Entertainment, and YG Entertainment have also been aggressively pursuing global strategies, albeit with varying approaches to artist comeback frequency and international promotions.
While specific Q3 reports from all competitors might not be directly comparable without detailed analysis, general trends indicate a strong demand for K-pop content globally. However, even industry leaders face challenges, including market saturation, intense competition, and the evolving digital consumption habits of audiences. The impact of foreign exchange rates, as highlighted by SM Entertainment, is a common external factor that can affect any company with significant international operations. For instance, a strong Korean Won makes it more expensive for international fans to purchase Korean merchandise or concert tickets, while also reducing the value of repatriated foreign earnings when converted back to Won. This underscores the volatile environment in which global entertainment companies operate.
SM Entertainment’s Recent Corporate History: A Period of Flux
The Q3 results also come after a tumultuous period for SM Entertainment. The past year saw a high-profile corporate battle for control of the agency, involving founder Lee Soo-man, rival agency HYBE Corporation (home of BTS), and South Korean tech giant Kakao. This intricate power struggle ultimately led to Kakao emerging as the largest shareholder in March 2023, effectively ending Lee Soo-man’s long-standing influence over the company he founded.
This change in ownership and management ushered in a new era for SM Entertainment, often referred to as "SM 3.0," promising a multi-production center system, IP monetization acceleration, and a renewed focus on global expansion. The Q3 results, therefore, can be viewed through the lens of this transition. The reported strategic shift towards overseas activities and the temporary reduction in domestic releases might be an intentional part of the "SM 3.0" vision, aimed at restructuring the company’s operational model for long-term global sustainability rather than short-term domestic sales maximization. Such significant corporate restructuring often entails initial disruptions and recalibrations before the new strategies fully materialize in financial performance.
Investor Reaction and Market Dynamics
The immediate 7% drop in SM Entertainment’s stock price on November 4 clearly indicates a negative reaction from investors. While the company’s strategic rationale for prioritizing overseas activities might be sound for long-term growth, the short-term financial dip, particularly the net loss, triggered concerns among shareholders. Investors often prioritize predictable revenue streams and consistent profitability, and a sudden decrease in core album sales, even if explained by a strategic pivot, can lead to volatility.
Market analysts will now be closely scrutinizing SM Entertainment’s future guidance and the detailed execution of its global strategy. The question for the investment community will be how quickly the increased revenue from MD/licensing and artist appearances can compensate for the reduced album sales and whether the overseas activities will translate into significantly higher, sustainable profits in subsequent quarters. The currency headwinds, being largely external, add another layer of uncertainty, although their impact can be mitigated through hedging strategies.
Looking Ahead: Strategic Outlook and Future Prospects
Moving forward, SM Entertainment faces the dual challenge of reassuring investors of its long-term vision while demonstrating tangible improvements in its financial performance. The success of its strategic pivot will hinge on several factors:
- Effective Monetization of Global IP: Continuing to grow MD/licensing revenue and explore new avenues for IP utilization globally.
- Optimizing Overseas Activities: Ensuring that international tours, promotions, and appearances are highly profitable and efficiently managed.
- Balanced Release Schedule: Potentially recalibrating the frequency of major domestic comebacks to maintain a baseline of album sales without detracting from global initiatives.
- New Artist Debuts: Introducing new groups or solo artists that can contribute fresh revenue streams and capture new fan segments, both domestically and internationally.
- Currency Risk Management: Implementing robust strategies to mitigate the impact of foreign exchange fluctuations.
The K-pop industry is dynamic, and SM Entertainment, as one of its foundational pillars, has consistently adapted to changing trends. The unprofitable Q3, while a setback, could be interpreted as a necessary growing pain in the pursuit of a more globally integrated and diversified business model. The upcoming quarters will be crucial in determining whether this strategic shift will indeed pave the way for sustained international growth and renewed profitability for the K-pop powerhouse. The success of groups like NCT 127 in maintaining sales despite fewer overall releases underscores the enduring strength of SM’s artist roster, but the broader strategic vision will require careful execution to fully realize its potential.
